
If you searched for UPI charges hoping for a simple yes-or-no answer, here’s the honest one: as of today, ordinary UPI payments are still free but that changes in less than a month. On September 15, 2026, the government and NPCI confirmed a new Merchant Discount Rate framework taking effect October 15, 2026, and it genuinely does introduce a fee on certain UPI payments above ₹2,000 just not the way most people assume.
At SocioLabs, we work with e-commerce brands and service businesses who need to understand exactly how payment changes affect their operations, not just their marketing. This guide breaks down precisely who pays what, starting when, and what your business should check before the new rule kicks in.
Are UPI Payments Above ₹2,000 Charged?
Starting October 15, 2026, person-to-merchant (P2M) UPI payments above ₹2,000 fall into a three-slab MDR structure set by NPCI but person-to-person (P2P) transfers remain completely free at any amount, and merchant transactions at or below ₹2,000 stay unaffected too.
This is a genuine, recently confirmed policy change, not a rumor. It reverses the zero-MDR policy that’s applied to UPI merchant payments for six years, since India made UPI and RuPay debit card transactions free to drive adoption back in 2020. Before this announcement, the Finance Ministry had explicitly denied any plans to introduce UPI charges as recently as mid-2025 so if you read an older article confidently saying “UPI above ₹2,000 has no fee,” that was accurate when it was written, but it’s now outdated.
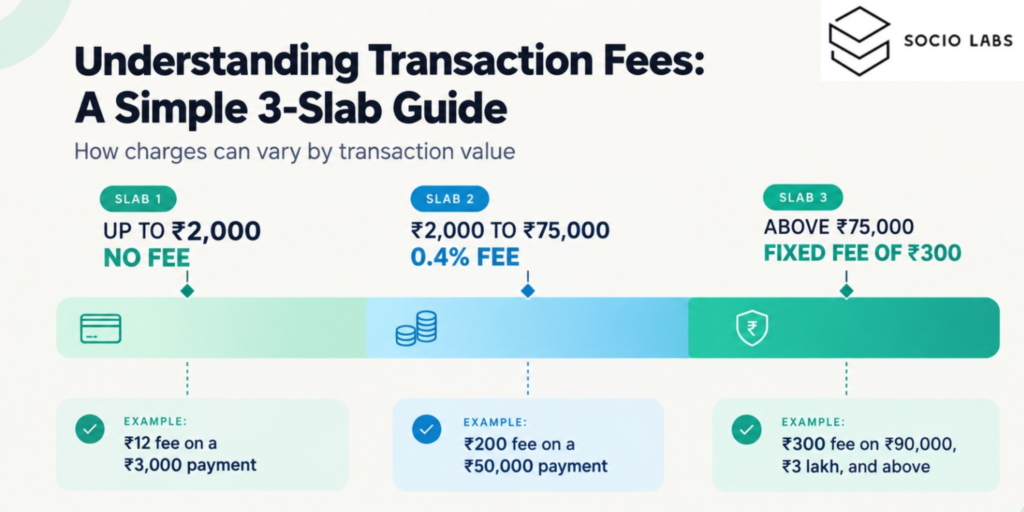
NPCI’s own structure what one ET Tech graphic labeled “The MDR Math” breaks down into three clear slabs:
|
Slab |
Transaction Range |
Fee |
Example |
|
Slab I |
Up to ₹2,000 |
No fees |
Always free |
|
Slab II |
₹2,000 to ₹75,000 |
0.4% |
₹12 fee on a ₹3,000 payment; ₹200 fee on a ₹50,000 payment |
|
Slab III |
Over ₹75,000 |
Flat ₹300 |
₹300 fee on a ₹90,000 payment, a ₹3 lakh payment, or higher |
The math behind the ₹75,000 breakpoint is straightforward: 0.4% of ₹75,000 is exactly ₹300, so above that point NPCI simply fixes the fee at ₹300 rather than letting it keep scaling with transaction size a shopkeeper accepting a ₹3 lakh payment pays the same ₹300 as one accepting ₹90,000.
The transaction type matters just as much as the slab. A friend paying you back ₹5,000 for dinner (P2P) pays nothing, ever, regardless of slab. A customer paying a shop ₹5,000 for goods (P2M) falls in Slab II, and the shop not the customer absorbs a ₹20 charge starting mid-October.
What Are UPI Charges and Who Actually Pays Them?
UPI charges refer to fees that can apply at different points in the payment chain the customer, the merchant, the merchant’s bank, or the payment app provider and a charge existing somewhere in this chain doesn’t automatically mean the customer pays it.
Under the new October 2026 framework, the 0.4% MDR on qualifying P2M transactions is split among ecosystem participants: the customer’s bank receives the largest share, followed by the merchant’s acquiring bank (around 30%), the UPI app provider (around 20%), and partner banks (around 10%). None of this share goes to the customer, and none of it is billed to the customer directly.
- Customer: Pays nothing under the new framework P2P is always free, and P2M under ₹2,000 stays free
- Merchant: Pays the 0.4% MDR on qualifying P2M transactions above ₹2,000
- Issuing bank, acquiring bank, UPI app provider: Share the MDR revenue among themselves
- Payment gateway/aggregator: May charge separate, provider-specific fees regardless of NPCI’s MDR rules
Why Is the ₹2,000 UPI Limit or Threshold Often Mentioned?
The ₹2,000 figure has appeared in UPI policy discussions for years, originally as the boundary for a government incentive scheme protecting small transactions, and now specifically as the exemption threshold in the new MDR framework payments at or below ₹2,000 remain fully free, while the new 0.4% charge applies only above that line for merchant payments.
This is genuinely confusing because ₹2,000 has meant different things at different times. Historically, it marked the boundary for a subsidy scheme keeping small merchant transactions free for banks. Now, under the October 2026 rule, it’s specifically the exemption line below it, merchants pay nothing; above it, merchants may owe the new MDR.
Critically, this threshold applies to P2M (merchant) transactions only. Person-to-person transfers of any amount ₹500 or ₹5,00,000 remain entirely outside this framework and free for everyone involved.
Do Customers Pay a Fee for UPI Payments?
No under the new framework, customers do not pay a fee for UPI payments of any kind, whether person-to-person or person-to-merchant, at any transaction amount.
The Finance Ministry has been explicit that this new MDR framework does not create any consumer-facing UPI fee the entire structure is designed to charge participating merchants, not the person paying.
Do Businesses Pay Charges on UPI Payments?
Yes merchants accepting P2M UPI payments above ₹2,000 will pay MDR according to NPCI’s three-slab structure starting October 15, 2026, though specific merchant categories get a different, simpler flat-fee arrangement.
Standard merchant QR and bank-account UPI acceptance follows the slab structure: nothing up to ₹2,000, 0.4% between ₹2,000 and ₹75,000, and a flat ₹300 above ₹75,000. Specific categories railways, telecom services, insurance, and fuel get a flat ₹5 per transaction instead of the percentage-based slab for any payment above ₹2,000, regardless of how large the transaction gets. Capital market transactions (mutual funds, broker payments) carry a separate, smaller rate structure of their own.
The Finance Ministry has framed this shift as making UPI “self-sustainable” after six years of zero-cost operation, and the change directly benefits the banks and payment app providers processing these transactions including major players like PhonePe and Google Pay who share in the new MDR revenue.
Businesses using PPI wallets (like certain prepaid wallet apps) as their acceptance method have separately operated under an interchange charge structure on transactions above ₹2,000 for wallet-based payments a distinct, older arrangement from the new October 2026 P2M slab structure, worth checking with your specific payment provider since the two can overlap depending on setup.
UPI MDR Explained: What Businesses Should Know
MDR (Merchant Discount Rate) is the fee a bank charges a merchant for accepting a digital payment for UPI specifically, it’s been nil since 2020, but NPCI’s new three-slab structure changes that for most P2M transactions above ₹2,000 starting October 15, 2026.
Who receives it? The customer’s bank, the merchant’s acquiring bank, and the UPI app provider including large players like PhonePe and Google Pay split according to a defined revenue-sharing structure.
Who pays it? The merchant accepting the payment never the customer directly, and never added as a separate line-item charge to the buyer.
Does it apply to every UPI transaction? No. P2P transfers are permanently exempt. P2M transactions at or below ₹2,000 (Slab I) remain exempt. Categories like railways, telecom, insurance, and fuel follow a flat ₹5 fee instead of the percentage-based slabs.
How should businesses verify applicable charges? Check directly with your bank or payment aggregator for your specific merchant category classification, and confirm which slab your typical transaction sizes fall into ₹12 on a ₹3,000 sale and ₹300 on a ₹3 lakh sale are very different economics depending on your average ticket size.
UPI Charges for Businesses: Real-World Examples
|
Payment Type |
Example Amount |
Slab |
Fee Charged to Merchant |
|
Bank-account UPI, standard retail |
₹1,500 |
Slab I |
No fee below ₹2,000 |
|
Bank-account UPI, standard retail |
₹3,000 |
Slab II |
₹12 (0.4%) |
|
Bank-account UPI, standard retail |
₹50,000 |
Slab II |
₹200 (0.4%) |
|
Bank-account UPI, standard retail |
₹90,000 |
Slab III |
Flat ₹300 |
|
Bank-account UPI, standard retail |
₹3,00,000 |
Slab III |
Flat ₹300 (same as ₹90,000) |
|
Fuel/telecom/insurance/railways |
₹3,000 or higher |
Category-specific |
Flat ₹5, regardless of slab |
|
PPI wallet acceptance |
₹5,000 |
Separate framework |
Wallet interchange fee (provider-specific, not part of this slab structure) |
|
Person-to-person transfer |
Any amount |
Not applicable |
No fee always free |
UPI Payment Charges vs Payment Gateway Charges
UPI itself, under NPCI’s rules, is a separate thing from what a payment gateway or business payment platform charges you a business can owe zero NPCI-mandated MDR on a small transaction while still paying its payment gateway provider’s own commercial fee for the same transaction.
This distinction causes real confusion. A business might say “my payment provider charges 2% on UPI,” which sounds like it contradicts “UPI is free” but both can be true simultaneously. The provider’s fee is a commercial charge for their service (checkout integration, reconciliation tools, settlement speed), separate from NPCI’s own MDR framework.
Always ask your payment gateway or aggregator to clearly separate their own service fee from any NPCI-mandated MDR pass-through, so you know exactly what you’re paying for and why.
What Should Businesses Check Before Accepting Large UPI Payments?
- Confirm your merchant category classification with your bank or aggregator
- Ask your payment provider exactly how they’ll implement the October 15, 2026 MDR change
- Review your current payment gateway pricing separately from NPCI’s MDR
- Check your settlement terms and whether MDR gets deducted before or after settlement
- Confirm your GST and tax documentation correctly reflects any new MDR deductions
- Review your refund process for transactions where MDR may have already been charged
- Check applicable transaction limits for your merchant category
- Confirm fraud and security controls remain unaffected by the pricing change
- Ask what merchant support is available if billing discrepancies appear after October 15
Common Myths About UPI Charges
Myth: “Every UPI payment above ₹2,000 has a fee.” Not quite only person-to-merchant payments above ₹2,000 are affected from October 15, 2026; person-to-person transfers remain free at any amount.
Myth: “Customers always pay UPI charges.” False under the new framework, customers pay nothing; the MDR is charged to the merchant.
Myth: “Merchants always pay MDR on UPI.” Not universally merchant payments at or below ₹2,000, and some small-merchant categories, remain exempt.
Myth: “All UPI transactions have the same pricing.” False P2P, standard P2M, flat-fee categories (railways, telecom, fuel), and capital market transactions all have different structures.
Myth: “UPI and payment gateway charges are the same thing.” False NPCI’s MDR and a payment provider’s own commercial pricing are separate and can both apply independently.
Myth: “This is just a rumor that keeps circulating.” No longer accurate while similar claims were denied by the Finance Ministry in 2025, this specific framework was officially confirmed on September 15, 2026.
Myth: “PPI wallet charges and the new MDR are the same rule.” No PPI wallet interchange fees have existed separately for longer; the new October 2026 framework is a distinct addition covering standard bank-account P2M transactions.
What Businesses Should Do in 2026
- Verify your merchant category and confirm which pricing tier applies to you
- Contact your bank or payment aggregator directly for their October 15, 2026 rollout plan
- Avoid relying on older articles that state UPI has zero MDR that changed as of this announcement
- Communicate clearly with customers if your pricing needs to adjust, without implying they’re being charged
- Monitor your settlement reports closely in the weeks after October 15 for any discrepancies
- Keep your payment processes and documentation updated as your provider implements the change
Conclusion
UPI charges are shifting in a real, confirmed way for the first time since 2020 a 0.4% MDR on person-to-merchant payments above ₹2,000 begins October 15, 2026, while person-to-person transfers and smaller merchant payments stay free. Customers aren’t charged under this framework; the responsibility sits with merchants, who should confirm their specific category and provider rollout before the change takes effect. At SocioLabs, we help businesses navigate exactly this kind of operational shift alongside their broader digital growth strategy, since payment changes often ripple into customer communication and marketing decisions too.
Navigating payment changes is one part of running a growing business building the marketing engine around it is another. Explore our performance marketing services to make sure your growth strategy keeps pace with operational changes like this one.
FAQs
Starting October 15, 2026, person-to-merchant UPI payments above ₹2,000 carry a 0.4% MDR paid by the merchant; person-to-person transfers remain free at any amount.
No under the new framework, customers pay nothing for UPI payments of any kind; all applicable charges are directed to merchants, not buyers.
Yes, on qualifying person-to-merchant payments above ₹2,000, merchants pay a 0.4% MDR starting October 15, 2026, with some categories charged a flat ₹5 instead.
MDR (Merchant Discount Rate) is the fee merchants pay to the banks and payment providers processing a transaction, newly applicable to most UPI P2M payments above ₹2,000 from October 2026.
Not exactly ₹2,000 is the exemption threshold; transactions at or below that amount remain free, while the fee applies only to qualifying amounts above it.